Skip to content
guide · insurance & risk

Personal trainer insurance: what you need and what it costs.

Yes, most online personal trainers need insurance. You still give exercise and nutrition advice that a real person acts on, often alone at home, so professional liability is the core cover, with public liability added for any in-person or hybrid work. A signed waiver is not enough on its own. Before you buy, check that the policy names online or virtual sessions and covers the countries your clients live in.

Coaching from an app does not remove the risk that a client gets hurt, blames your programming, or disputes a payment; it just changes where the risk shows up. This guide covers the main types of personal trainer insurance, roughly what it costs, which policies cover online and virtual sessions, how to make a claim, and the everyday steps that lower your risk before a claim ever happens.

By Markus Evers · Updated November 2026

the short answer

Personal trainer insurance is liability cover that protects a coach - in person or fully remote - if a client claims their programming or advice caused injury or financial loss. Most trainers carry professional (civil) liability as the core policy, and add public liability for any in-person work. Premiums vary by country, cover limits, and claims history.

Online personal trainer insurance, usually a mix of professional (civil) liability and public liability cover, protects your business and your income if a claim ever lands. Smart screening, signed agreements and staying in your scope make it far less likely you ever need to use it.

As dated context, US insurer Insurance Canopy lists its most popular personal-trainer policy at USD 159 per year as of November 2026, a concrete example of the modest annual range this cover usually sits in; see what personal trainer insurance costs by cover type. UK insurer Insure4Sport describes the core cover plainly: "Personal trainer insurance through Insure4Sport can protect you, your PT business, and your clients in the event of accidents, injury, or other unexpected events, either at the gym or in private sessions."

This is general information, not legal or insurance advice. Insurance requirements vary by country and state - check your local rules and speak to a licensed broker.
why it matters

Why online coaching still carries real risk.

A common assumption is that working remotely removes liability - no shared gym floor, no hands-on spotting, so nothing to be sued over. That is not how it works. You are still giving health and exercise guidance that a real person acts on, often alone in their own home, sometimes with an injury or condition you never asked about. If something goes wrong, the fact that it happened through an app does not make the claim disappear. A thorough online fitness assessment reduces the odds, but it does not erase the exposure.

Online coaching also adds risks that in-person trainers rarely think about. You hold client data - health questionnaires, progress photos, sometimes payment details - which makes a data breach a real, if quiet, liability. Many coaches who call themselves "online" still run the occasional retreat, workshop, or in-person assessment, which pulls public liability back into scope. And selling at distance makes refund and results disputes more common than they are in a face-to-face gym relationship.

This is why online coaching insurance and good day-to-day practice work together rather than as alternatives. Insurance for online coaches is the financial backstop if a claim succeeds. Screening, agreements, scope discipline, and clean records are what stop most claims from ever reaching that point. Carry the cover, and build the habits that mean you rarely lean on it.

types of cover

Types of cover online personal trainer insurance includes.

Most online trainers do not need every policy below, but you should know what each one does so you can ask a broker for the right mix. Availability and names differ by region, so treat this as a map, not a shopping list.

  • Professional or civil liability (often called professional indemnity) - the core policy for most online trainers. It responds to claims that your coaching, programming, or advice caused a client injury or financial loss.
  • Public liability - covers injury to another person or damage to their property. It matters the moment you do anything in person: a free assessment, a pop-up session, a retreat, a workshop, or filming on location.
  • Equipment and contents cover - protects the gear your business actually runs on: laptop, phone, camera, lighting, and any home-studio kit you coach or film from.
  • Cyber and data liability - relevant once you store client health information, progress photos, or payment details. It responds to a data breach and the costs that follow it.
  • Product liability - worth asking a broker about if you sell physical products like supplements, equipment, or branded gear alongside your coaching.
  • Personal accident or income protection - optional, but some trainers add cover for their own income in case an injury stops them coaching for a stretch.
what it costs

How much does personal trainer insurance cost?

For a solo personal trainer, basic liability insurance is usually a modest yearly cost, not a large monthly bill. At the time of writing, US insurers publish prices from about USD 160 a year for general and professional liability bundled together, and median prices of roughly USD 350 to 500 a year for each of those policies bought separately. UK specialist insurers advertise public liability plus professional indemnity from under GBP 50 a year. Equipment, nutrition-advice and cyber cover cost extra. Your actual price depends on your country, cover limits, deductible, any in-person work and your claims history.

Cover type Published price example Source
General + professional liability, bundled (US)USD 159 a year, or USD 15 a monthInsurance Canopy
General liability on its own (US)Median about USD 350 a yearInsureon
Professional liability on its own (US)Median about USD 500 a yearInsureon
Public liability + professional indemnity + small equipment cover (UK)From GBP 3.86 a month on an annual policyProtectivity
Add-ons: equipment, nutrition advice, cyber (US)About USD 1 to 13 a month eachInsurance Canopy

Insurers' own published figures, checked 24 October 2026. Insureon figures are medians of quotes requested through Insureon. Prices change and are examples, not quotes. A standalone cyber policy can cost far more than an add-on.

Which cover you need: in person, online or hybrid

Usually yes, even where no single law requires it. What you need depends on how you coach:

  • In person: public liability plus professional liability is the standard pair, and many gyms and venues ask for proof of cover before you train clients there.
  • Online: professional liability is the core policy, because a client still does your program, often alone. Check that the policy covers remote and international clients; some insurers attach conditions to online coaching, such as a signed PAR-Q and a consultation call before the first session, and recommend recording live sessions.
  • Hybrid: carry both. One in-person assessment, workshop or retreat brings public liability back into scope.

Rules vary by country, employer and certifying body, so confirm your requirements with a licensed broker.

online and virtual sessions

Which personal trainer insurance covers online and virtual sessions?

Do not assume a personal trainer policy covers online coaching. Some were written with gyms and client homes in mind, so the policy name tells you little. Read the wording, or ask the insurer in writing, and check these six points before you buy.

  1. 01

    Online or virtual sessions are named

    The wording, schedule or FAQ should say it covers live online sessions or remote coaching. If it only mentions gyms, studios and client homes, treat online work as not confirmed.

  2. 02

    Pre-recorded programs and app-delivered plans

    A program a client follows on their own time is not the same as a live video call. Check that pre-recorded sessions, written programs and plans delivered through an app are covered, not only live classes.

  3. 03

    Nutrition advice scope

    Some insurers leave diet and nutrition advice out of professional liability and sell it as a separate add-on. If you write meal plans or set macro targets, make sure that work is named in your cover.

  4. 04

    Territory and jurisdiction

    Online clients can live anywhere. Check which countries the policy covers, whether a claim brought in another country is covered, and whether any country is excluded. The territory on a policy built for in-person training may not match where your online clients live.

  5. 05

    Claims-made or occurrence

    An occurrence policy covers incidents that happened while it was active, even if the claim arrives years later. A claims-made policy covers claims made while it is active, usually back to a retroactive date, so if you switch insurer or stop coaching you may need run-off or tail cover.

  6. 06

    Conditions you have to meet

    Some policies attach conditions to online coaching, such as a signed PAR-Q before the first session or a consultation call. Read them before you sell, because breaking a condition can put a claim at risk.

What four insurers say about online cover

These are the insurers already cited on this page, with what their own pages say about online work. They are examples, not recommendations, and terms change.

  • Insurance Canopy (US) says its policy covers trainers who teach live online classes or offer pre-recorded sessions, and that occurrence form cover is included. Diet and nutrition advice is not covered by its professional liability and needs a separate add-on.
  • Insureon (US) says trainers who offer virtual training, such as materials clients use on their own time, can still get coverage, and that coverage terms differ between insurers.
  • Insure4Sport (UK) covers live or pre-recorded online sessions for trainers who also see clients in person, and offers worldwide cover as an add-on for up to six months a year. It says it cannot provide personal trainer cover if all your sessions are online and you never see clients in person.
  • Protectivity (UK) covers remote coaching, live or pre-recorded, if you meet its conditions, including a signed PAR-Q before the first session and a consultation call. Its standard cover is for teaching in the UK; outside the UK needs an overseas extension, so ask how that applies to online clients abroad.

Checked on each insurer's own page on 4 November 2026. If you coach only online, or most of your clients live in another country, say so when you ask for a quote and get the answer in writing.

risks and cover

Common online-coaching risks and how cover addresses them.

The point of this table is not to scare you. It is to show that insurance and good practice each handle a different half of the same problem. The left column is what can go wrong, then why it still applies online, then how cover and habits address it together.

What could go wrong Why it still applies online How cover and good practice help
Client injured doing your programThey train alone, off-camera; a poorly suited or badly cued exercise can still hurt themProfessional liability responds to the claim; PAR-Q screening and scaled programming cut the odds
Advice blamed for a health setbackYou may not know a client's full medical history or medicationsCivil liability covers the claim; intake screening and staying in scope keep you on safe ground
Client disputes results or wants money backSelling at distance makes refund and results disputes more frequentMostly a contract issue: a clear written refund policy and records settle most of them
Client data or progress photos leakYou store health questionnaires, photos, and sometimes payment detailsCyber or data liability responds; a secure platform and storing less reduce exposure
Someone hurt at an in-person sessionMany online coaches still run retreats, workshops, or live assessmentsPublic liability covers third-party injury or property damage at in-person events
Laptop or filming gear lost or damagedYour whole business runs on a few pieces of kitEquipment and contents cover replaces it quickly so you keep coaching
how to reduce risk

How to reduce your risk as an online trainer.

Insurance is the backstop. These five habits are what keep you from needing it. Build them into how you onboard and run every client, and most disputes never start.

  1. 01

    Screen every client before you program anything

    Use a structured intake and a PAR-Q health questionnaire so you know about injuries, conditions, medications, and red flags before you prescribe a single set. Coachway check-in and intake forms let you build this once and send it to every new client, and our guide on how to do a fitness assessment online walks through what to ask.

  2. 02

    Put it in writing with an agreement and waiver

    A signed coaching agreement and a liability waiver set out what you do, what you do not do, and the fact that the client is exercising at their own risk. Good paperwork does not replace insurance, but it lowers the odds of a dispute and shows the client understood the terms.

  3. 03

    Stay inside your scope of practice

    You are a coach, not a doctor, physiotherapist, or dietitian. Refer out for injury rehab, medical conditions, eating-disorder signals, or prescription-level nutrition advice. Most claims and complaints come from advice given outside the lane you are actually qualified for.

  4. 04

    Set a clear refund and cancellation policy upfront

    Spell out billing, cancellation, and refund terms before the client pays, not after they ask. A written policy turns most money disputes into a quick reference rather than an argument. Our guide on how to handle a client who wants a refund covers the wording and the conversation.

  5. 05

    Keep good records

    Store the signed agreement, the completed PAR-Q, your programming notes, and your check-in history in one place. If a claim or dispute ever surfaces, a clear paper trail of what you advised and why is the single best thing you can hand a broker or a lawyer.

the paper trail, in practice

Could you pull up one client's full file in two minutes?

That is the practical test for your records, whatever tool you use: the intake answers, the completed PAR-Q and every check-in since week one, kept per client rather than scattered across email threads and loose PDFs. In Coachway, each client's intake answers and full check-in history sit on that client's profile, documents such as a signed agreement can sit in the file vault, and you can export your data as CSV or PDF when you need a copy. Software keeps the record; it does not replace the cover itself or a broker's advice on it.

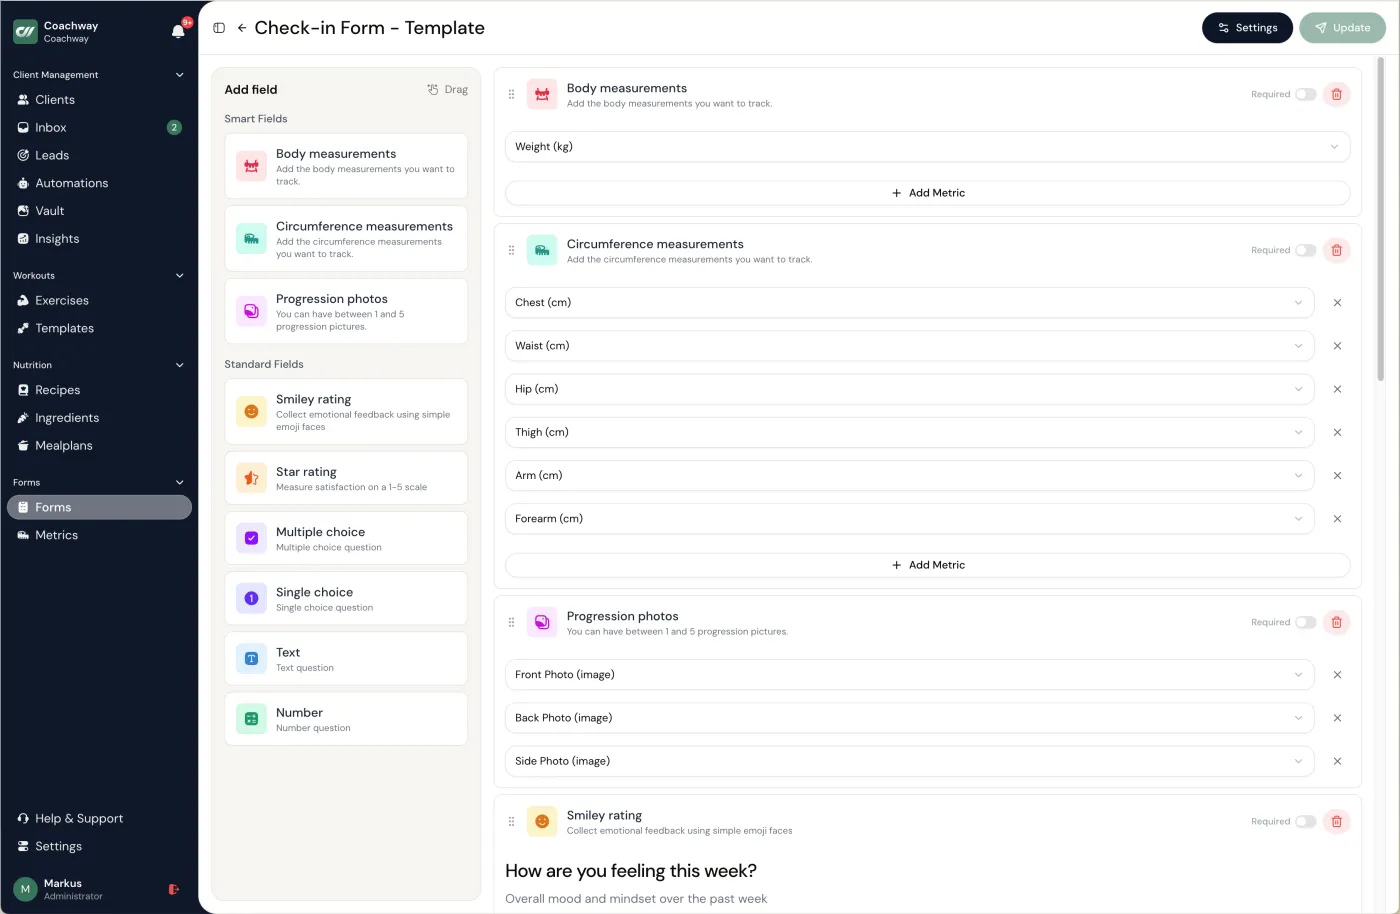
Inside Coachway Coachway forms - a check-in form builder with smart fields for measurements, photos and ratings
The check-in form builder, with smart fields for measurements, photos and ratings: write your intake and PAR-Q questions once, and every client's answers are filed with that client. See the form builder
build your intake form 14-day free trial. Card required, EUR 0 today, cancel anytime under Billing.
if something goes wrong

How to make a personal trainer insurance claim.

If a client gets hurt, complains, or threatens legal action, these six steps protect your claim. Your policy wording and your insurer's claims process come first, so read them alongside this list.

  1. 01

    Tell your insurer or broker straight away

    Report the incident, complaint or legal letter as soon as you hear about it, with your policy number to hand. Policies usually require prompt notice, and late notice can put cover at risk.

  2. 02

    Do not admit liability or offer money

    Stay polite and factual with the client, but do not accept blame, apologise in a way that admits fault, or offer a refund or payment as compensation without the insurer agreeing first. Many liability policies make this a condition.

  3. 03

    Write down what happened while it is fresh

    Note the date, the session or program involved, what the client reported, who was involved, and what you advised. Stick to facts; leave opinions out.

  4. 04

    Gather your records

    Pull together the signed coaching agreement and waiver, the completed PAR-Q, the program and any changes you made, the check-in history and your messages with the client, plus any session recordings.

  5. 05

    Pass legal letters on unanswered

    If the client or a lawyer sends a formal letter or claim, send it to your insurer and let them, or the lawyer they appoint, reply. Do not negotiate on your own.

  6. 06

    Follow the insurer's process and keep a log

    Fill in the claim form, answer the handler's questions, and keep a copy of every email, call and document. A clear log makes the claim faster and avoids disputes about what was said.

Step 4 is far easier if the paperwork existed before anything went wrong. Start every client with a PAR-Q form and a signed liability waiver, and keep them with the client's program and check-ins.

This is general information, not legal or insurance advice. Claims processes differ by insurer and country, so follow your own policy and ask your broker or insurer what they need.

lower your risk

Lower your risk and look more professional doing it.

The same habits that protect you legally also make your coaching feel more credible to the people deciding whether to trust you with their training. Risk reduction and a premium experience are the same project.

Screen and document

An intake form, a PAR-Q, a signed agreement, and a waiver collected before the first program. It protects you, and it tells the client you run a real business, not a side project.

Stay in your lane

Coach what you are qualified to coach and refer out the rest. Knowing your limits is not a weakness; it is the single clearest signal of a professional who can be trusted with someone's health.

Keep clean records

One place for agreements, screening, programming, and check-in history. If a dispute ever surfaces, a clear paper trail is what resolves it quickly and keeps a broker on your side.

None of this replaces a conversation with a licensed broker, but it is the part you fully control. Screen well, document everything, stay in scope, and keep your records tidy - the everyday risk of online coaching drops sharply, and the whole operation looks more professional to the clients deciding whether to commit.

questions coaches ask

Frequently asked questions.

Do personal trainers need insurance?

There is rarely a single law that forces every trainer to buy it, but most working personal trainers carry insurance because giving exercise advice a client acts on creates real liability. Professional or civil liability is the usual core policy, with public liability added for anyone who trains clients in person. What is actually required depends on your country, your employer, and the gym or venue you work in - many gyms and certifying bodies ask for proof of cover before they let you train. This is general information rather than legal advice, so confirm your local requirements with a licensed broker, whether you coach in a gym or run everything online on a coaching platform.

Do online personal trainers need insurance?

In most cases, yes. Even though you coach remotely, you are still giving health and exercise guidance that a real person acts on, and that creates real liability. Most online personal trainers and online coaches carry at least professional (civil) liability cover, and add public liability if they ever work in person. Requirements differ by country and state, and some certifying bodies or client contracts require proof of cover, so check your local rules.

What types of insurance do online coaches need?

The core policy for insurance for online coaches is professional or civil liability, which responds to claims that your advice or programming caused harm. Many add public liability for any in-person work, equipment cover for the gear they film and coach from, and cyber or data liability if they store client health information, photos, or payment details. A licensed broker can tell you which combination fits your setup and region.

How much does personal trainer insurance cost?

It depends on your country, cover limits, deductible, whether you work in person, and your claims history. At the time of writing, US insurers publish prices from about USD 160 a year for general and professional liability bundled, and medians of roughly USD 350 to 500 a year for each policy bought separately, so a bundle is normally cheaper than two separate policies; UK specialists advertise public liability plus professional indemnity from under GBP 50 a year. Equipment, nutrition-advice and cyber cover cost extra. Treat these as examples and get two or three quotes from licensed providers in your region.

What are the main types of online personal trainer insurance?

The main types are: professional or civil liability (the core policy, covering claims your advice or programming caused harm), public liability (for any in-person sessions, retreats, or workshops), equipment and contents cover (for the laptop, phone, and filming gear your business runs on), and cyber or data liability (relevant once you store client health data, progress photos, or payment details). A licensed broker can confirm which mix fits your setup and region.

Does a liability waiver replace insurance?

No. A signed waiver and a clear coaching agreement reduce your risk and help show a client understood and accepted it, but they do not pay legal costs or a settlement if a claim succeeds, and waivers can be limited or unenforceable depending on local law. Think of waivers and insurance as two layers: good paperwork lowers the odds of a claim, and insurance covers you if one lands anyway.

Where do online trainers get insurance?

Most online trainers buy through specialist fitness or personal-trainer insurance providers, general business insurers, or brokers, and some certifying and professional bodies offer member policies or discounts. Because online coaching can cross borders, confirm the policy covers remote and international clients if you have them. Speak to a licensed broker who understands coaching businesses before you buy.

Insurance is one piece of running a credible coaching business. If you are still setting up, the guide on how to become an online fitness coach walks through the agreements, screening, and systems that sit alongside cover. This is general information, not legal or insurance advice. Insurance requirements vary by country and state - check your local rules and speak to a licensed broker.

See what Coachway can do for your coaching business

Coachway was built on knowledge from working with 150 online coaches over 6+ years, who all hit the same wall - slow platforms, clunky workflows, wasted hours. Start your 14-day free trial and see what we fixed - the whole platform, no charge today, cancel anytime under Billing.

No charge today - cancel anytime under Billing
Built for efficiency 8 languages DenmarkNorwaySwedenFinlandGermanyNetherlandsSpainUnited Kingdom
The coaching platform you've been waiting for

Run your coaching in one place. Try Coachway free for 14 days. Coachway: 14 days free

Start free trial
